GTP News, Advice & Tips
Navigating the aged care system can feel overwhelming, particularly when faced with the complex terminology, means testing rules, and various fees that may apply. Many families worry about whether they can afford aged care or whether a loved one will need to sell their home to pay for care. The good news is that Australia's aged care system is heavily subsidised by the Government, and there are protections in place to ensure that everyone can access appropriate care regardless of their financial circumstances. What Fees Apply in Residential Aged Care? If a person moves into an aged care home, there are generally four categories of costs that may apply. 1. Basic Daily Fee The Basic Daily Fee is paid by almost all residents and contributes towards day-to-day living expenses such as meals, cleaning, laundry and utilities. It is set by the Government and indexed regularly. As at March 2026, the maximum Basic Daily Fee is approximately $66.80 per day. 2. Means-Tested Contributions Depending on a person's income and assets, they may be required to contribute towards the cost of their care through means-tested arrangements. For people entering aged care under the newer fee arrangements, contributions may include: · Hotelling Contributions · Non-Clinical Care Contributions These fees are determined following a financial assessment conducted by Services Australia and are subject to annual and lifetime caps. Some residents pay nothing beyond the Basic Daily Fee, while others may make additional contributions based on their financial capacity. 3. Accommodation Costs Accommodation costs are often the most significant expense and are determined by the aged care provider. Residents may pay for accommodation by: · A Refundable Accommodation Deposit (RAD), being a lump sum payment; · A Daily Accommodation Payment (DAP); · Or a combination of both. A RAD is generally refundable when the resident leaves care, less any agreed deductions allowed under the legislation. 4. Additional Service Fees Some aged care homes offer enhanced services beyond the standard level of care. These may include superior accommodation, upgraded meal options, lifestyle programs or additional amenities. Where applicable, providers can charge additional fees for these optional services. Do You Have to Sell the Family Home? One of the most common concerns families raise is whether the family home must be sold to fund aged care. The answer is often "not necessarily." The home is only one factor considered in the aged care means assessment, and various rules apply regarding how much of the home's value is counted. In many cases, families can choose between paying a RAD, a DAP or a combination of both, allowing flexibility in managing cash flow and preserving assets. However, the decision to retain or sell the family home can have significant consequences for: · Aged care fees; · Centrelink entitlements; · Estate planning objectives; · Cash flow requirements; and · Tax outcomes. This is why obtaining specialist aged care advice is often worthwhile before making any major financial decisions. What About Home Care? For older Australians who remain living at home, government-funded home care programs can help support independence. Under the Support at Home framework, contributions are generally determined by a person's income and assets. Clinical services are typically government funded, while contributions may apply to other support services depending on financial circumstances. Unlike residential aged care, there is generally no accommodation component because the individual continues living in their own home. Can Everyone Access Aged Care? A common misconception is that people with significant assets are not entitled to government-supported aged care, or that those with limited resources cannot afford care. In reality, all eligible Australians can access government-subsidised aged care services. The financial assessment process is designed to determine an individual's contribution, while government funding covers the balance of approved care costs. Key Takeaways When considering aged care, families should remember: · Everyone generally pays a Basic Daily Fee. · Additional contributions may be payable depending on income and assets. · Accommodation can be funded using a RAD, DAP or a combination of both. · The family home can significantly affect aged care outcomes. · Government subsidies ensure aged care remains accessible regardless of financial position. · Obtaining financial and aged care advice before entering care can potentially save considerable costs and avoid unintended consequences. Final Thoughts Aged care is one of the most significant financial decisions many families will face. While the fee structure can initially appear complex, understanding the different components and planning ahead can make the process far less stressful. The best outcomes are usually achieved when aged care planning is considered alongside estate planning, tax advice, Centrelink entitlements and broader family objectives. Taking the time to obtain advice before entering care can help ensure that both the older person and their family make informed decisions with confidence.
In close to 57 years, I have received a lot of advice from many sources. Starting from my parents, my friends, community members, work colleagues, mentors across these fields as well as my clients. Below are a few that stand out. Some of which I live by, some I need to take more notice of. 1. Treat others as you would like to be treated. If you can be anything in this world, be kind. 2. It is never as bad as you think and its never as good as you think. 3. If it sounds too good to be true it usually is. 4. If you have bad news to deliver, get it over and done with. The longer you wait the harder it will be to deal with for you and the recipient. 5. It is impossible to know everything. If you are stuck, ask for advice, decent people will always help. 6. Comparison is the thief of joy. 7. If you want to learn something, surround yourself with people who see things differently than you. Collaboration is a great problem solver. 8. Borrowing to invest magnifies your result. If it is a crap investment, you will lose more by borrowing. If it is a great investment, you will get a great return in the long run. 9. Understand the importance of community and contributing to community groups. Volunteering and doing things for others provides immeasurable rewards. 10. Investing in anything (bank deposits, shares, property) all involves risk – the secret is to understand the risk you are dealing with. 11. Making mistakes is part of life, just get better at not making the same mistake twice. 12. Every investment needs to pass a “sleep at night” test. If you cannot sleep at night, do not invest in it. This test is different for every individual. 13. If you have a “bucket list” of things you want to do – tell others! Telling others will massively increase the chances of you achieving your bucket list items, because people will want to help you with your list. 14. Compounding investment returns are the eighth wonder of the world. 15. Measure your progress, it is OK to count your money. 16. Experience the thrill and energy of live music! 17. The only way to grow is by putting yourself in unfamiliar and uncomfortable situations. 18. The best time to invest is yesterday. 19. Be curious, it is amazing what you might find out. 20. Invest regularly, automatically and for the long-term, it pays off big time! 21. The best investment you can make is investing time and money with the people that mean the most to you. Invest in meals, get togethers, laughter, weekends with special friends and family – there is nothing like it!
In today’s digital world, scams are becoming increasingly sophisticated and widespread. As accounting professionals, we see firsthand how scams can impact businesses and individuals, from identity theft to fraudulent invoices. It’s more important than ever to stay vigilant and take proactive steps to protect your finances and sensitive information. Common Scams Targeting Australian Businesses Phishing Emails: These are emails that appear to be from legitimate organisations, such as the ATO or your bank, asking you to click a link or provide sensitive information. Invoice Scams: Fake invoices are sent, often with subtle changes to the payee details. Business Email Compromise: Cybercriminals hack email accounts and impersonate executives or suppliers, requesting urgent payments or confidential data. Tax Scams: Fraudsters pose as the Australian Taxation Office, demanding payment, threatening legal action, requesting changes be made to your MyGov account. Warning Signs to Watch Out For Scammers are crafty, but there are tell-tale signs to help you spot a dodgy approach: Unexpected requests for payment or personal information Spelling and grammar mistakes in emails or messages Unusual urgency or pressure to act quickly Inconsistencies in email addresses or payment details Requests to transfer funds to unfamiliar accounts How to Protect Yourself and Your Business Verify Before You Pay: Always double-check invoice details and payment requests, especially if they’re unexpected. Get on the phone and confirm with the supplier directly. Educate Your Team: Make sure your staff know the risks and signs of scams. Hold regular training sessions and circulate updates about new scam tactics. Use Strong Passwords: Ensure all accounts use strong, unique passwords. Consider multi-factor authentication for extra security. Update Software Regularly: Keep your systems and antivirus software up to date to patch vulnerabilities. Secure Your Data: Back up important files and restrict access to sensitive information only to those who need it. Report Suspicious Activity: If you suspect a scam, contact the ACCC’s Scamwatch or your bank straight away. Early reporting can help prevent further losses. What To Do If You’ve Been Scammed If your business falls victim to a scam, don’t panic. Immediately contact your bank, the police, and your accountant. Preserve any evidence and report the incident to Scamwatch (www.scamwatch.gov.au). Quick action is key to minimising potential harm.
How to Process Payday Super in MYOB & Xero From 1 July 2026, employers are required to pay superannuation at the same time employees are paid. To avoid ATO penalties, super contributions must generally be received by the employee’s super fund within 7 business days of payday. If you use MYOB or Xero payroll, the process is straightforward, but it is important to submit and authorise super payments as soon as possible after each pay run. Processing Payday Super in MYOB Super is processed directly through MYOB. The super amounts will prefill based on the pay runs processed. To process and authorise super in MYOB: In MYOB, go to ‘Payroll’ then click ‘Super payments’ It will ask you to ‘login’, click login Click the green ‘create super payment’ button in the top right corner Select all super payments (these should all be from the pay run just processed), and click ‘record’ Click ‘yes’ and continue to authorise payment Click ‘authorise’ Click ‘get code’ which will send an SMS to the authorised mobile number Enter the code into the ‘authorisation code’ field and click ‘authorise’ The ‘Success!’ message should appear, and the status updated to ‘processing’ Once the payment is processing, you do not need to do anything else, the super payment will be automatically direct debited from your nominated bank account. Processing Payday Super in Xero Super is processed directly through Xero. The super amounts will prefill based on the pay runs processed. To process and authorise super in Xero: In Xero, go to ‘payroll’ then click ‘superannuation’ Click ‘add super payment’ or click into the box ‘X unpaid contributions’ Select the super payments (if multiple, then select all) Click ‘submit for approval’ on the right-hand side Click ‘continue to approve’ Enter the SMS authorisation code sent to your phone, then click ‘verify and pay’ Once approved and verified, the batch status updates to ‘processing’ Once the payment is processing, you do not need to do anything else, the super payment will be automatically direct debited from your nominated bank account. Need assistance with Payday Super? If you’re unsure whether your payroll setup is ready for these requirements, contact your accountant. We can help review your payroll processes and ensure super payments are being processed correctly and on time.
How long can you chase a debt? Unpaid debts are a fact of life in business. But there is a limit on how long you can legally recover them — and it’s something that often gets overlooked until it’s too late. So, how long do you actually have? The short answer In most cases (including Victoria), you’ve got 6 years to take legal action to recover a debt. After that, the debt becomes what’s called “statute-barred.” That doesn’t mean it disappears, but it does mean: you can’t enforce it through the courts, and your leverage to recover it drops significantly It’s not always a straight 6 years Here’s where it gets tricky. The 6-year clock doesn’t just run and expire, it can reset. If the debtor: makes a payment (even a small one), or acknowledges the debt in writing the clock starts again from that date. We see this a lot with older debtor balances that have had small, sporadic payments over time. A few quick exceptions Just to round things out: Court judgment? You may have up to 12–15 years to enforce it Secured debts (e.g. property)? Usually longer again ATO debts? Different rules entirely, they don’t follow the same 6-year limit Practical tips for managing old debts This is where it really matters for business owners. If you’ve got older receivables sitting there, here are a few simple checks: 1. Know the age of your debts Don’t just look at the balance, look at when it was last paid or acknowledged That’s what determines your real timeframe. 2. Don’t leave recovery too long If a debt is getting close to 6 years: consider escalating it earlier or making a call on whether it’s worth pursuing Waiting too long can remove your legal options completely. 3. Be careful with partial payments Even a small payment: can restart the 6-year clock which can work in your favour (or against you) 4. Clean up your books regularly Old debts sitting on the balance sheet can: overstate your financial position create tax complications Regular reviews help you decide whether to recover, write off, or formally deal with them. The takeaway As a rule of thumb: 6 years is your window for most debts but the timing isn’t always obvious and small actions can reset the clock If you’ve got older debts sitting there and aren’t sure where they stand, it’s worth reviewing them sooner rather than later, a quick check now can save you losing the ability to recover them altogether.
Minimum Wage Increase Effective from 1 July 2026 Australian workers received a pay rise following the Fair Work Commission's 2026 Annual Wage Review. From 1 July 2026, the National Minimum Wage increased to $26.44 per hour, while minimum award wages increased by 4.75%. These new rates applied from the first full pay period starting on or after 1 July 2026. For employees, the increase may provide some relief from ongoing cost-of-living pressures. It's a good idea to review your payslip and ensure your employer has applied the updated rates correctly. For business owners, the change serves as an important reminder to review payroll systems, employee classifications and award coverage to ensure the new rates have been applied correctly. As the increase took effect from the first full pay period on or after 1 July 2026, employers who have not yet updated their wage rates should act urgently. Any underpayments should be identified and rectified as soon as possible to avoid ongoing compliance issues and potential penalties. Reviewing wages now can help ensure your business remains compliant and employees receive their correct entitlements. If you're unsure whether the increase affects your business or your employees, Green Taylor Partners can help you understand your obligations and ensure you remain compliant.
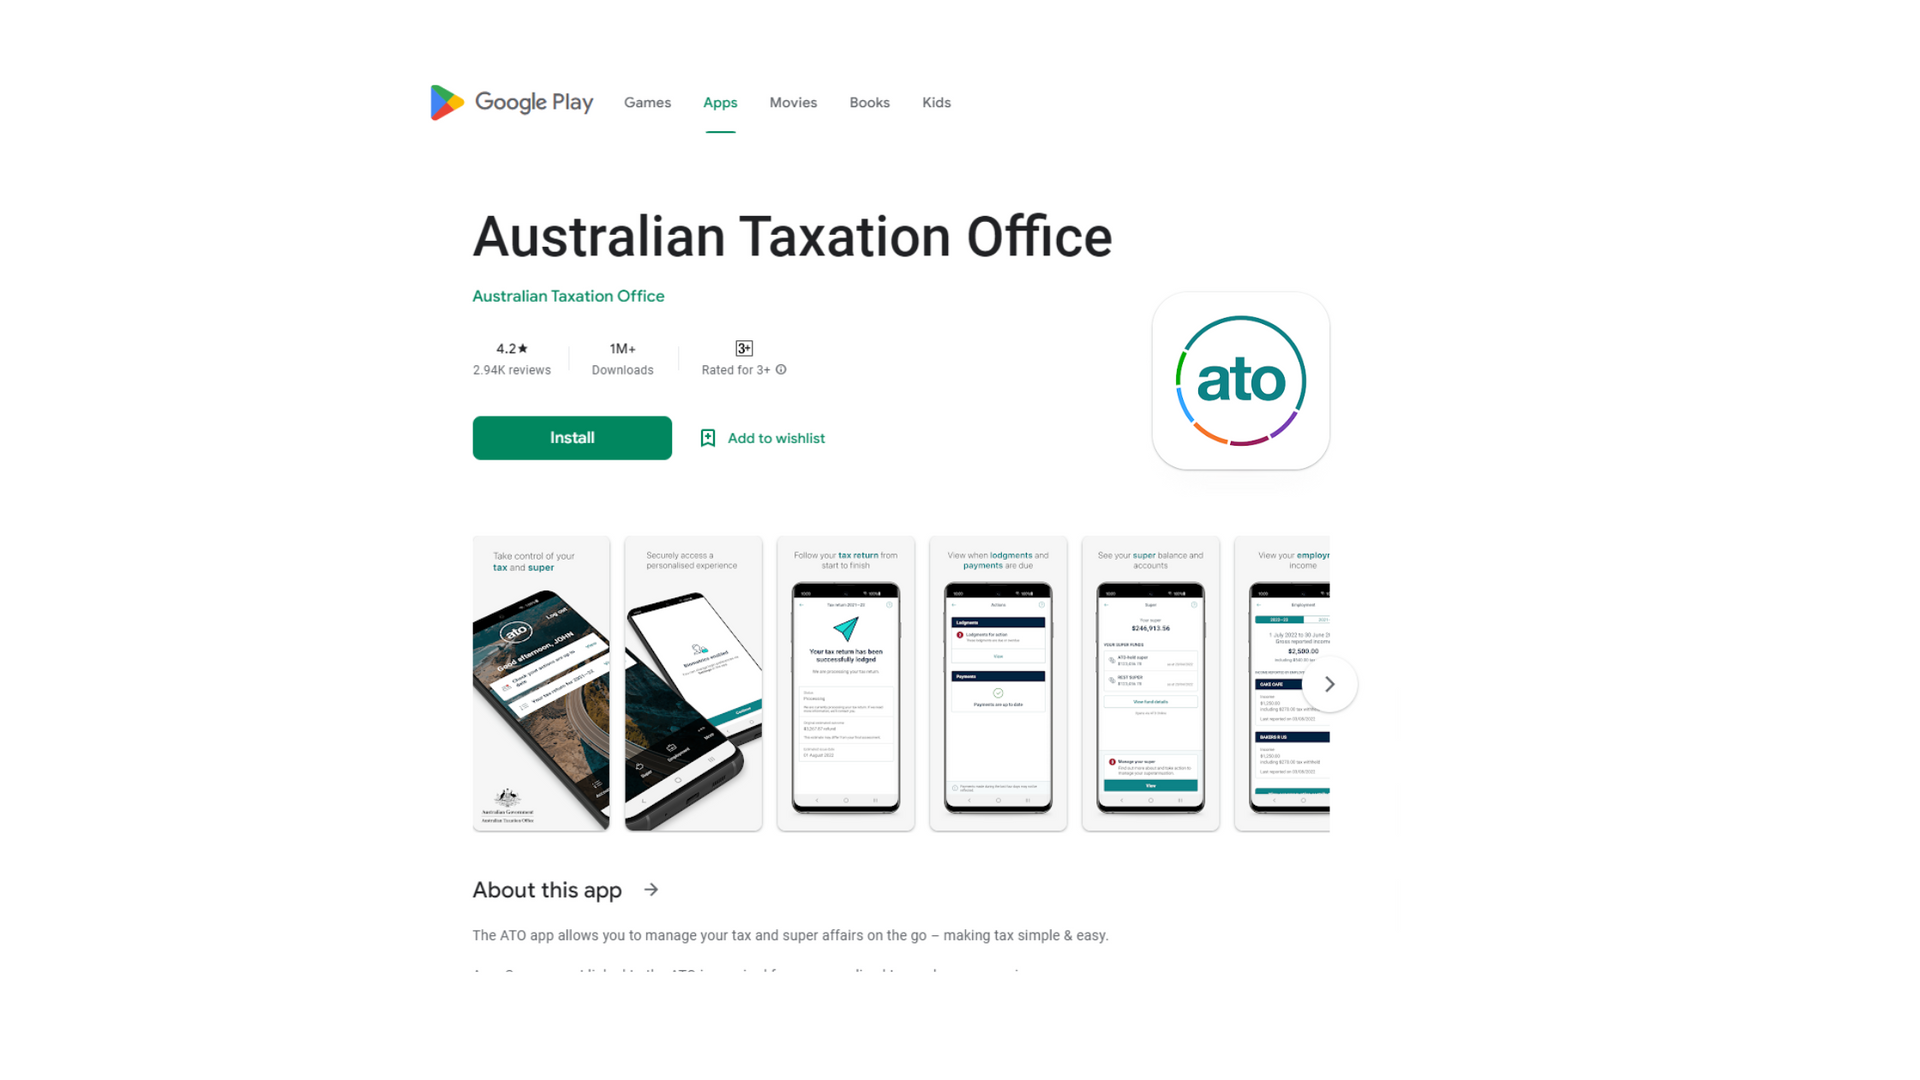
New ATO App Feature Helps Protect You From Scam Calls With tax time approaching, scam activity always ramps up and unfortunately, many of these scams involve fraudsters pretending to be from the Australian Taxation Office (ATO). To help combat this, the ATO has recently introduced a new feature within its app that allows you to verify whether a call is genuinely from the ATO in real time. You can read the official announcement here: ATO launches new app feature to stop scam calls What Is the New “Verify Call” Feature? The ATO has introduced a new “verify call” function in its mobile app that allows you to confirm if a call is genuinely from the ATO - while you are still on the phone. It works in real time and gives you an immediate answer, helping remove the guesswork when you receive an unexpected call. The goal is simple: put control back in your hands so you can quickly identify and shut down scam attempts. How It Works If you receive a call from someone claiming to be from the ATO, you can: Open the ATO app on your phone Log in securely Select the “verify call” option If the call is legitimate, you will receive a confirmation notification within approximately 30 seconds. If you do not receive a notification, you should treat the call as a scam and hang up immediately. What To Do If You Receive a Scam Call If you receive a suspicious call, SMS, email or social media message: Do not reply, click on any links or download any attachments. Visit verify or report a scam to check or report it. Call the ATO immediately on 1800 008 540 , if personal information or payment has been shared with a scammer. Visit ato.gov.au/scamsafe for more information on how to protect personal information and stay safe from scammers.
As we move into the new financial year, there is a noticeable shift in conversations with clients across Western Victoria. Whether you operate a grain and livestock enterprise, a family-owned retail store, or a manufacturing business servicing regional Australia, the themes remain remarkably similar. Many regional businesses are generating strong earnings, but are also facing increasing tax, compliance and cash flow pressures. The Three Issues We're Discussing Most With Clients 1. Cash Flow Remains King Despite profitability improving for many businesses, cash flow continues to be the biggest challenge. Higher wages, increased superannuation costs, rising insurance premiums and elevated interest rates mean that profitable businesses can still feel cash constrained. For primary producers, fluctuating commodity prices and seasonal conditions add another layer of complexity. For retailers, consumer spending remains selective, while manufacturers continue to face margin pressure from labour and input cost increases. The businesses performing best are those that actively monitor: Debtor collection times Inventory levels Business debt levels Capital expenditure decisions Tax and superannuation obligations Strong cash flow management is becoming a greater competitive advantage than ever before. 2. The Compliance Environment Is Tightening The Australian Taxation Office continues to increase its focus on data matching and compliance activities. Areas attracting attention include: Trust distributions Division 7A loans Superannuation compliance GST reporting Property and capital gains transactions Business versus private expenditure claims Many business owners are surprised by how quickly information is now shared between government agencies, banks and regulators. Our advice remains simple: Good record keeping has never been more important. The cost of addressing compliance issues after the event is almost always higher than investing in quality systems and advice upfront. 3. Superannuation Is Becoming More Important One of the most significant changes affecting employers is the continuing evolution of superannuation obligations. Industry commentary during EOFY 2026 has focused heavily on the upcoming Payday Super regime, alongside increased employer super obligations and payroll system readiness from 1 July 2026. [wealthworks.com.au] , [aimsaustralia.com.au] , [moula.com.au] For business owners, superannuation should no longer be viewed solely as a compliance matter. It is increasingly becoming a strategic tool for: Tax planning Retirement funding Intergenerational wealth transfer Succession planning Asset protection For successful farming families and private business owners, the ability to move wealth into the superannuation environment often remains one of the most effective long-term planning opportunities available. Looking Ahead No one can accurately predict weather patterns, interest rates or global markets. What we can control are the fundamentals. The most successful businesses in regional Victoria continue to focus on: ✅ Understanding their financial position ✅ Managing cash flow carefully ✅ Investing in people and systems ✅ Reviewing structures regularly ✅ Planning for succession early ✅ Seeking advice before decisions become problems Businesses that plan proactively almost always have more options than those that wait until issues arise. The start of a new financial year is an ideal time to step back, review where your business is heading, and ensure your structure, finances and strategy remain aligned with your long-term objectives.
From 1 July 2026 , new anti-money laundering (AML) and counter‑terrorism financing (CTF) laws will apply to many accounting firms across Australia. While this is primarily a compliance change for us as your adviser, you will notice some changes in how we work with you. This article explains what’s happening and what it means in practical terms. What’s changing? The Australian Government is expanding its AML/CTF laws (known as “Tranche 2 reforms”) to include professions like accountants, lawyers and real estate agents. Previously, these rules mainly applied to banks and financial institutions. From July 2026, many accounting firms will also be regulated by AUSTRAC (the government financial intelligence agency). These changes are designed to: · Reduce fraud, tax evasion and financial crime · Bring Australia in line with international standards · Close gaps where advisers may unknowingly be used to move or disguise funds Why this matters for your business As your accountant, if we provide certain services (such as setting up companies or trusts, managing funds, or assisting with ASIC transactions), we must now follow strict compliance procedures. This means you may be asked for additional information or documentation. What you can expect to change More identity checks (‘Know Your Client’) We will need to verify your identity and, in some cases, the identity of related parties (e.g. directors, shareholders or beneficiaries). This may involve: · Providing photo ID · Confirming ownership structures · Updating details periodically Even long‑standing clients may be required to complete this process. Additional questions about your business activities We may ask further questions to better understand: · What your business does · Where funds come from · The purpose of certain transactions These are part of our obligations to assess the risk of financial crime. More documentation requests Depending on the service, we may request documents such as: · Contracts or transaction details · Source of funds evidence ● Trust deeds or company records, if we don’t already hold these This is a standard requirement under the new laws. Timing of work may be affected Some services cannot commence until required checks are completed. To avoid delays, we recommend: · Responding promptly to information requests ● Providing complete documentation upfront Ongoing monitoring (in some cases) For certain engagements, we may be required to: · Periodically update your information ● Review transactions or changes in your structure What won’t change Importantly: · Our role as your trusted adviser remains the same · Your information remains confidential and secure ● We will only request what is required under law Why this is ultimately a good thing While these changes will add some extra steps, they are aimed at: · Protecting legitimate businesses like yours · Strengthening the integrity of Australia's financial system · Reducing fraud and misuse of business structures In short, it helps ensure a fairer and safer business environment for everyone. What you need to do now There’s nothing you need to action immediately, but over the coming months you can: · Expect some new onboarding or update requests · Ensure your business records and ID documents are readily available ● Let us know of any changes to your structure or ownership We’re here to help We understand these changes may feel like “more paperwork”, particularly for long‑term clients. Our goal is to make this process as smooth and practical as possible while meeting our legal obligations. If you have any questions about how these changes apply to your business, please feel free to get in touch.
For many Australians, a holiday home offers the best of both worlds — personal enjoyment and short‑term rental income through platforms like Airbnb or Stayz. However, recent draft guidance from the Australian Taxation Office (ATO) suggests that owners need to take a closer look at how these properties are treated for tax purposes. The ATO’s latest guidance makes it clear that earning some rental income does not automatically mean a property qualifies for full tax deductions . Instead, the focus is on whether the property is genuinely operated as an income‑producing investment or whether it is primarily a lifestyle asset. Investment Property or Lifestyle Asset? While all rental income must be declared, the ATO may restrict expense deductions where a property is mainly used for private purposes and only rented when convenient. If a property is classified as a holiday home rather than a genuine rental property, deductions for expenses such as interest, council rates, land tax, insurance and general maintenance may be denied. In many cases, owners may only be able to claim limited, direct costs associated with specific guest stays, such as cleaning or advertising. What Will Attract ATO Attention? The ATO is particularly focused on properties that: Are unavailable for rent during peak periods such as school holidays Are advertised inconsistently or priced above market rates Generate ongoing tax losses year after year Are clearly prioritised for personal use over rental income While no single factor is decisive, these patterns can indicate that the property is not being run on a commercial basis. Apportionment and Records Matter Where a property qualifies as income‑producing but is used partly for private purposes, expenses must be apportioned fairly and reasonably. Good records are critical, including booking calendars, listings, rental enquiries and notes of private use. The ATO can access booking platform data and readily cross‑check claims. What Should Owners Do Now? Although the draft guidance is proposed to apply from 1 July 2026, now is the time to review your position. Owners should consider whether their property is genuinely operated to maximise rental income, whether pricing reflects market conditions and whether their record‑keeping would stand up to scrutiny. Final Takeaway The ATO isn’t banning deductions for holiday homes, but it is taking a firmer approach to distinguishing investment properties from lifestyle assets. A proactive review now can help avoid unexpected tax outcomes later. If you own a holiday property and are unsure where you stand, a proactive review could help protect your position and improve your tax outcome. Please contact us if you would like assistance assessing your current arrangements.
Capital Gains Tax (CGT) – What You Need to Know (and What’s Changing) If you own investments like property, shares, or a business, understanding Capital Gains Tax (CGT) is critical—especially with major changes on the horizon. What is Capital Gains Tax? Capital Gains Tax (CGT) is the tax you pay on profits when you sell an asset. It applies to assets acquired after 19 September 1985 Your capital gain is simply: Sale price (what you sell it for) minus Cost base (what you paid + associated costs) If the result is positive → you have a taxable capital gain If negative → you have a capital loss Do you always pay tax on the full gain? Not always. There have historically been concessions to reduce your tax bill, depending on when you bought the asset and how long you held it. The Two Main CGT Methods (Historically) 1. Indexation (Pre-1999 assets) This older method adjusted your cost base for inflation so you were only taxed on the real gain. Only applies to assets acquired on or before 21 September 1999 Adjusts the purchase cost using CPI This method is no longer available for newer assets. 2. The CGT Discount (Current system) This is the most common method used today. If you: hold an asset for more than 12 months, and are an eligible taxpayer (individual, trust, or super fund) You may reduce your capital gain: 50% discount for individuals and trusts 33.33% discount for super funds Example: If you make a $100,000 gain, you may only pay tax on $50,000 How CGT is Taxed Your net capital gain is added to your income It’s taxed at your marginal tax rate Capital losses can’t reduce other income—but can be carried forward Major CGT Changes Coming (From 1 July 2027) The government has proposed significant reforms that will change how CGT works. 1. The 50% Discount is Being Replaced From 1 July 2027: The current 50% CGT discount will be removed Instead, we return to a form of indexation Meaning: You’ll only be taxed on gains above inflation This is designed to tax the “real” gain only 2. A New Minimum 30% Tax Rate A key change: A minimum tax rate of 30% will apply to capital gains What this means: If your tax rate is below 30% → you still pay 30% If your rate is above 30% → you pay your normal rate The 30% is a floor, not a cap 3. Existing Assets – How Will They Be Treated? If you already own assets, the rules will split your gain into two periods: Before 1 July 2027 Existing rules apply (including the 50% discount) After 1 July 2027 New rules apply (indexation + 30% minimum tax) In practice: You may need a valuation at 1 July 2027 to determine the split 4. What About Pre-1985 Assets? Historically: Assets bought before 20 September 1985 were completely CGT-free From 1 July 2027: Any future growth in those assets will become taxable Past gains remain tax-free 5. Special Rule for New Housing To support housing supply: Investors in new residential property may choose between: The old 50% discount, or The new indexation method + minimum tax What This Means for You These changes could significantly impact: Investment property owners Share investors Business owners Family groups and trusts Key implications: The timing of asset sales will become more important Valuations at 1 July 2027 may be critical Tax outcomes could increase for lower-income taxpayers Long-term investment strategies may need review Final Thoughts Capital Gains Tax has always been complex—but the upcoming changes make planning even more important. If you own, or are thinking about selling: Property Shares A business Or any investment asset it’s worth reviewing your position well before 1 July 2027.
While most of the media focus around the 2026 Federal Budget has been on things like negative gearing and housing, one of the biggest changes has barely been mentioned at all — the taxation of discretionary trusts. And if you’re a small business owner or part of a family that uses a trust, this change could materially affect how your income is taxed in the future. Introduction One of the most significant outcomes of the 2026 Federal Budget isn’t aimed at the so‑called ‘top end of town’. It is aimed squarely at structures that everyday mum‑and‑dad businesses rely on. From 1 July 2028, discretionary trusts will be subject to a minimum 30% tax on taxable income, fundamentally changing how trust distributions are taxed. What Was Announced Under the measures announced in the 2026 Federal Budget: • Discretionary trusts will pay a minimum of 30% tax on their taxable income • That tax will be withheld by the trustee • Beneficiaries will receive a non‑refundable tax credit for the tax already paid by the trust Why This Is a Big Deal for Individual Beneficiaries Under the current system, a trust distribution to an individual is taxed at the individual’s marginal tax rates, allowing access to the $18,200 tax‑free threshold and currently a 16% tax rate on income up to $45,000. Under the proposed rules, this benefit effectively disappears. Even beneficiaries with total taxable income below $45,000 will still bear an effective 30% tax on trust distributions. Why Small Businesses Are Most Affected Discretionary trusts are widely used by small businesses including trades, farming operations, professional practices, and family‑run enterprises. While paying wages instead of trust distributions may address the tax outcome, if your business does not already have employees it introduces real additional costs such as payroll software, payday superannuation compliance, Single Touch Payroll obligations, and WorkCover premiums. The Investment Company Issue A major concern with the proposed measures is how they apply where a company is a beneficiary of a trust, commonly referred to as ‘Bucket’ companies. Based on information released to date, companies do not appear to receive access to the non‑refundable tax credit. This creates the risk of double taxation and significantly undermines bucket company strategies commonly used to smooth income over multiple years and manage long‑term family tax outcomes. Another Common Structure Being Impacted Many small businesses operate through a company, but where all shares are owned by a discretionary trust. This has historically been prudent tax and succession planning, allowing flexibility, family involvement, and long‑term planning. While companies may continue to declare franked dividends to the trust, distributions from the trust to family members appear to be subject to the same minimum 30% tax outcome — even where that income represents the operating profit of the business. Practical Example Consider a modest family business earning $120,000 through a Trust. Under current rules, the Trust could be distributed across family members on low marginal tax rates, or at the least between Mum and Dad, therefore they would each have taxable incomes of $60,000. Currently Tax on that before Medicare and other offsets would be $17,576 combined. Under the new measure that same profit would result in tax of $36,000, an increase of $18,424 in tax paid! For a business operation we would strongly suggest wages be paid of at least $45,000 to each of Mum and Dad. If the same profit is from Trust where all income is from investments there may not be the justification of wages. Final Thoughts Although these measures are not scheduled to commence until 1 July 2028 and further legislative details are still to be released, the implications for small business owners and families using trusts are significant. This article is general information only and does not constitute tax advice.
We’re seeing an increase in company clients receiving correspondence that closely resemble ASIC annual company renewal notices . While these notices can look official, they’re often sent by private businesses that are not associated with ASIC. They typically offer optional services at a cost well above the actual ASIC renewal fee. Before paying anything, we recommend taking a moment to check the following: Who it’s from – Genuine ASIC renewal notices come directly from ASIC, or from our office if we act as your registered agent. The details – Official ASIC correspondence will include your Corporate Key and clear ASIC branding. The tone – These notices often use urgent or threatening language to encourage quick payment. If you receive an invoice or notice and aren’t sure whether it’s legitimate, please contact our office before making payment. We’re happy to review it with you and help ensure you don’t pay for unnecessary services.
It’s common to inherit land, shares or other investments and assume there won’t be any tax to think about. While inheriting an asset usually doesn’t trigger capital gains tax (CGT) straight away, CGT can become an issue later—particularly when you decide to sell. What affects the CGT outcome? · When the deceased originally acquired the asset (especially whether it was before or after 20 September 1985 ). · What the asset is (a home, an investment property, farmland, shares, a business asset, etc.). · Whether it was ever used to produce income (for example, rented out) or used in a business. · Who owned it and how (for example, owned jointly, or inherited through multiple generations). Questions we commonly ask (because the answers can change the result): · When did the deceased buy the asset? (And was it inherited from an earlier estate?) · Was the asset originally purchased with someone else (for example, a spouse or sibling)? · Was the asset used in a business (and could any small business CGT concessions apply)? As a general rule, there’s usually no CGT event when you inherit an asset . However, if you sell the inherited asset later, CGT may apply—and the calculation often depends on when the deceased acquired the asset and how it was used . If the inherited asset is a home: the main residence exemption may still apply after the owner’s death, but it can depend on things like when the deceased moved out, whether the property was rented, and who lived in the property after death. Cost base (the starting point for CGT): for many inherited assets, your cost base will depend on whether the deceased acquired the asset before or after 20 September 1985 . In broad terms, if the asset was owned by the deceased before that date, the cost base is often the market value at the date of death . If it was acquired after that date, the cost base is generally carried over based on the deceased’s position (with adjustments in some cases). Where the asset is connected to a business, small business CGT concessions may be relevant. If you’re thinking about selling something you inherited, it’s worth getting advice early—before contracts are signed—so we can confirm what records you’ll need and what the CGT position is likely to be.
It is Federal Budget night on May 12 and even though you may not be an excited accountant or tax agent counting down the days, if you are an investor, it is likely there will be changes announced which will impact you. The change which is likely to be unveiled will be the Albanese Government’s approach to capital gains tax, targeting mainly share and property investors, but will also impact business owners who sell business assets. It is likely the Albanese Government will re-introduce an inflation indexation model for calculating capital gains tax. This proposed change has gained more traction in the media over the last few weeks. Currently, individual taxpayers and trust beneficiaries are able to reduce their capital gains tax on the sale of any capital investment by 50 per cent, providing this investment has been owned for at least 12 months. Please note – superannuation funds receive only a one-third discount. For an individual, this means half the gain is tax free, the remaining half of the gain is taxed at the taxpayer’s marginal tax rate. This discount system on capital gains has been in place since 1999. Capital gains tax (CGT) was introduced in 1985 and is applied to realised gains and losses on assets acquired after 19 September 1985. If an asset was purchased prior to the introduction of CGT, then it is exempt from CGT when sold. From 1985 to 1989 an indexation system was used where inflation factors were applied to the original cost, so only the “real/after inflation” gain was taxed. At this stage there has been no indication whether the changes, if introduced, would be grandfathered, to spare existing investors from any initial pain.
Keeping a car logbook is an important part of managing your vehicle expenses, especially if you’re looking to maximise your tax deductions and GST claims or reduce your FBT liability. The Australian Taxation Office requires you to keep a logbook for a minimum continuous period of 12 weeks to establish your business-use percentage. Each trip should include the date, start and end times, kilometres travelled, and the purpose of the journey. Your logbook needs to reflect your typical vehicle use and can generally be relied on for up to five years, as long as your usage doesn’t significantly change. You’ll also need to record your vehicle’s odometer readings at the start and end of each FBT year and financial year. For many small business owners and tradies, keeping a car logbook is necessary but often pushed aside during busy workdays. Manually recording trips can be time-consuming, and it’s easy to forget details after the fact. There are now several apps available that reduce the manual effort of keeping a logbook. One we often recommend, which complies with ATO requirements, is Driversnote. Driversnote is designed to simplify the process by using GPS tracking to automatically record trips. This helps ensure journeys are logged consistently without relying on manual entry. Trips can be easily categorised as business or personal, and the app generates reports that align with ATO logbook requirements. This can make it easier to stay organised and provide accurate information at tax time. The app also stores data securely and keeps a history of trips, which can be useful if you ever need to review your records. For those who regularly use their vehicle for work, tools like Driversnote offer a practical way to maintain a logbook without the usual hassle—helping keep everything accurate, organised, and in one place. If you’re unsure whether a logbook is right for your situation, contact us— one of our team can help you work out the best way to track your vehicle use and ensure your records are accurate for FBT and tax time.
The Federal Government has once again extended the $20,000 instant asset write-off , providing continued support for small businesses looking to invest and grow. Under the latest legislation, eligible businesses can access the $20,000 threshold for assets first used or installed ready for use between 1 July 2025 and 30 June 2026 . This extension means businesses can continue to immediately deduct the full cost of qualifying assets, rather than depreciating them over several years. How the write-off works The instant asset write-off allows small businesses with an aggregated turnover of less than $10 million to claim an immediate deduction for assets costing less than $20,000 (excluding GST). The threshold applies on a per-asset basis , meaning multiple assets can be written off, provided each individual item is under the limit. Eligible assets can include tools, equipment, vehicles (subject to other limits), and office technology. Both new and second-hand assets may qualify, provided they are used for a business purpose. A critical point often missed is timing. It’s not enough to purchase an asset before 30 June— it must be installed and ready for use by that date to qualify for the deduction. What happens to assets that are above $20,000? If an asset exceeds the $20,000 threshold, it cannot be immediately written off in full. Instead, it is allocated to the small business general depreciation pool and depreciated over time. Under current rules, assets in this pool are typically depreciated at 15% in the first year and 30% in each subsequent year (on a diminishing value basis). This means the tax deduction is spread across multiple years rather than claimed upfront. Why the extension matters This measure continues to deliver meaningful cash flow benefits. By bringing forward deductions, businesses can reduce taxable income in the current year, freeing up funds for reinvestment or day-to-day operations. However, the extension is temporary. From 1 July 2026 , the threshold may revert back to just $1,000 unless further legislation is passed. This ongoing uncertainty makes forward planning essential so talk to your accountant today to plan ahead.
Fringe Benefits Tax (FBT) is a separate tax from GST and income tax that applies when a business provides benefits to employees or other associates. With the FBT year ending on 31 March , now is the time to review any benefits provided over the past 12 months to ensure you remain compliant. Understanding Fringe Benefits? A fringe benefit is any non-cash benefit, reimbursement, or expense paid by a business that is provided instead of, or in addition to, salary and wages. A simple way to think about it is if the business is paying for a personal expense or private use of a business asset, it may be a fringe benefit. Who FBT Applies To? FBT may apply where benefits are provided to individuals who are employees or are otherwise associated with the business. This includes: Employees Company directors Associates of employees or directors (including family members) Trust beneficiaries who are involved in, or connected to, the business For example, where a director is provided with the use of a company vehicle for private purposes, an FBT liability may arise irrespective of whether the director receives remuneration in the form wages. For businesses operating through a company or trust structure, it’s important to remember that the business is a separate legal entity . This means personal use of business assets is treated similarly to providing a benefit to an employee. Important Exception Sole traders or partnership owners using their own business assets personally do not trigger FBT. However, FBT can still apply if these businesses provide benefits to employees. Common FBT Areas for businesses While FBT can apply in many situations, the most common areas we see are: 1. Car Fringe Benefits If an employee, director or associate uses a company car for private purposes, FBT applies. Even parking the car at home overnight counts as personal use. TIP - Use the logbook method to track business-related travel and reduce FBT liability. 2. Entertainment Benefits Providing employees, directors or associates with free meals, drinks, and staff events (such as Christmas parties) may be subject to FBT. TIP - Limit to under $300 per person for minor benefits exemption, as this threshold deems the value insignificant. 3. Expense Payment Benefits If the business pays for personal costs on behalf of an employee or associate, this may be considered a fringe benefit. TIP - It’s important to distinguish between personal and work-related expenses. If the expense is work-related, the employer may be able to classify it as a business expense instead. 4. Housing and Accommodation Benefits Providing employees with rent-free housing or at a reduced rent can trigger FBT. TIP - Employers may be eligible for exemptions if housing is necessary for employees in remote areas or living away from their usual place of residence to carry out their duties. What you should to do If you believe you may be providing a fringe benefit to an employee, director, or associate, we recommend the following: Ensure accurate records and supporting documentation are maintained Complete the annual FBT questionnaire provided by Green Taylor Partners Provide all relevant information to enable us to assess whether FBT applies and assist you in meeting your compliance obligations
The answer to this question from an accounting perspective is generally to do with the difference between profit and cash. What is Cash? Cash is the money available in your bank right now. Cash is what is used to pay for business expenses such as rent and wages, or to purchase stock or assets. It can also be used to pay personal expenses. What is Profit? Profit = Business Income – Business Expenses Profit is the amount of money left on paper, after all business expenses have been deducted from your sales. The Difference Between Cash and Profit: Where Did The Money Go? Even when your business is making a profit, it is still possible to have little cash available in your bank. Here’s why: Unpaid Sales Invoices You send an invoice to a customer for $20,000 in May. · Sales revenue is recognised · Your profit increases · But if the customer hasn’t paid yet, your cash hasn’t increased. You may have to pay tax on the profit – even though you haven’t received the money yet. Loan Repayments You repay $10,000 off a business loan · Your cash decreases by $10,000 · Your loan balance decreases · Your profit does not decrease Only the interest paid on a loan is an expense that reduces profit. The principal repayment simply reduces a liability on your balance sheet. Plant & Equipment Purchases You purchase equipment for $50,000 · But you may not be able to claim the full $50,000 as an expense in the year the money is spent (depending on depreciation rules) For example, under small business depreciation rules, you may only claim $7,500 (15%) in year one. This means: · Cash is down $50,000 · Profit only reduces by $7,500 in the first year Owner withdrawals You transfer $20,000 from the business to your personal account · Your cash decreases · But this is not a business expense – it does not reduce profit. Drawings are simply moving money out of the business. Why This Matters for Business Owners Many small businesses struggle understanding the difference between cash and profit. Monitoring your cash balance and your profit regularly is essential. It is possible to be profitable and have a tax bill but have no cash available to pay for it. Want to know what your profit for 2026 is looking like – and how to plan for your tax bill? Book in with your accountant here at Green Taylor Partners to review your cash flow and tax position.
Tax time doesn’t always end with a refund. For some individuals and small businesses, it can result in a tax debt that’s difficult to pay by the due date. The good news is that the Australian Taxation Office (ATO) has several options available to help taxpayers manage their obligations. If you find yourself in this situation, it’s important not to ignore the debt. Acting early usually means more options and less stress. 1. Set Up a Payment Plan One of the most common options is entering into a payment plan with the ATO. This allows you to pay off your tax debt in smaller instalments over time rather than in a single lump sum. Payment plans are available to both individuals and small businesses and can often be set up online through your myGov account or via your tax agent. The ATO will generally consider factors such as: The size of the debt Your payment history Your ability to pay over time Interest may apply to outstanding balances, but a payment plan can make the debt much more manageable. From 1 July 2026 interest charged is no longer tax deductible. 2. Request a Short-Term Payment Deferral If you only need a little extra time, the ATO may allow a short-term extension to the payment due date. This option may suit taxpayers who are waiting on incoming funds, such as: Business income Insurance payments Loan approvals Other receivables A short extension can help avoid immediate collection action while you organise your finances. 3. Apply for Remission of Interest or Penalties If your circumstances are exceptional, you may be able to request remission (reduction or cancellation) of interest or penalties applied to your tax debt. The ATO may consider remission where: You’ve experienced serious illness or natural disaster You’ve made a genuine effort to comply Circumstances outside your control prevented payment Each request is assessed on a case-by-case basis. 4. Speak With Your Tax Agent A registered tax agent can often help negotiate a suitable arrangement with the ATO on your behalf. They can also review your financial position and make sure you’re accessing all available options. Many taxpayers find this approach less stressful than dealing with the ATO directly. There are however some cases where the ATO will only speak with you, or where you are better placed to explain the circumstances leading to the debt. 5. Contact the ATO Early The most important step is to communicate early. The ATO is generally more flexible when taxpayers engage before the situation escalates. You can contact the Australian Taxation Office by: Calling the ATO on 13 11 42 for individuals Calling 13 72 26 for business enquiries Logging into myGov and accessing ATO online services Speaking with your registered tax agent Final Thoughts Tax debt can feel overwhelming, but ignoring it rarely helps. Whether it’s a payment plan, deferral, or negotiating relief from penalties, there are options available. If you’re struggling to pay a tax debt, reach out early — either to the ATO or your Accountant at GTP — to put a plan in place and stay on track with your obligations.
